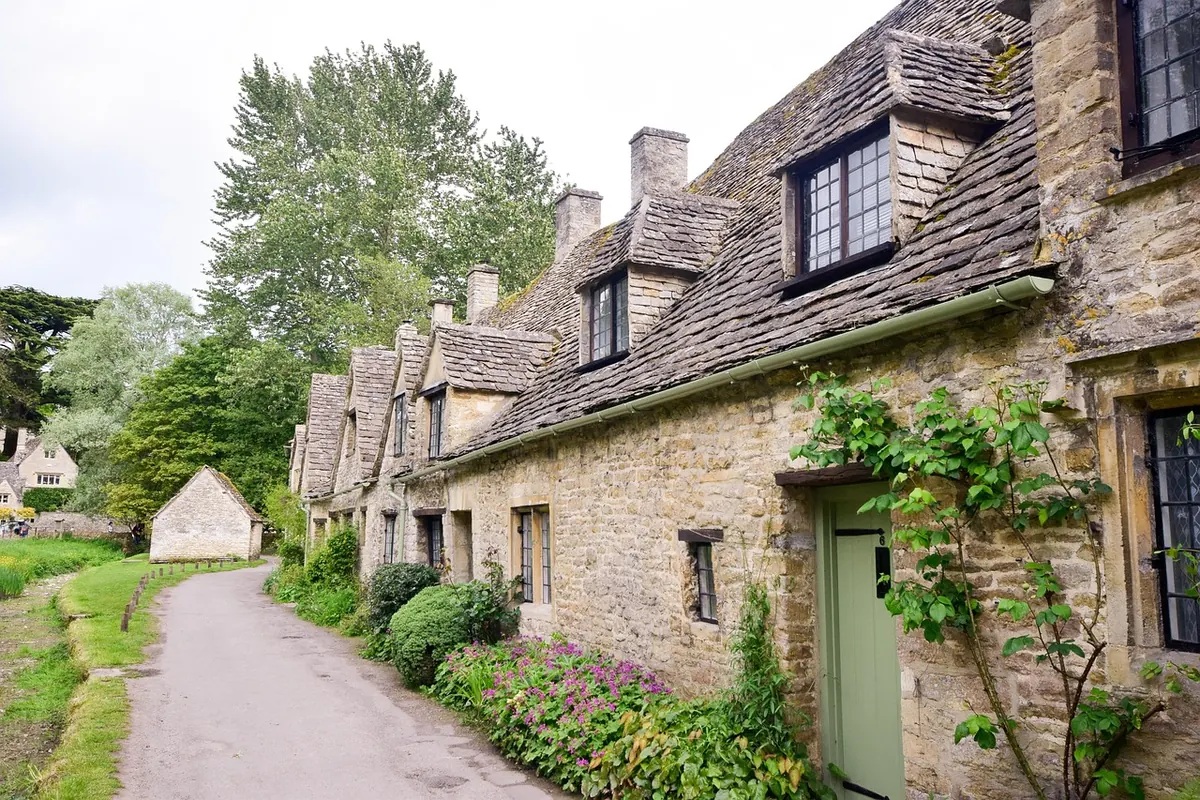
Buy a two-bedroom cottage in a Suffolk village and you have two ways to make it pay. Let it on a rolling tenancy and collect rent every month, or furnish it, photograph it properly and sell it by the night to people heading for Southwold, Aldeburgh or the Stour valley. Same building, different business. One is a steady asset that largely looks after itself; the other is a small hospitality company that happens to own a property. Deciding which of those you actually want to run matters more than any spreadsheet.
What each route can earn in Suffolk
Holiday let income comes down to two numbers: nightly rate and occupancy. In the right spot — a cottage within walking distance of Aldeburgh beach, a townhouse in Bury St Edmunds, a barn conversion near Lavenham — peak-week rates can be several times the nightly equivalent of a monthly rent. The catch is that Suffolk's season is real. July and August, half terms and the Christmas fortnight carry the year. January and February are quiet, and a wet bank holiday dents the total.
Long lets work the other way. The rent is lower, but it arrives whether it rains or not, minus the odd void between tenancies. Gross yields on a typical Ipswich or Bury house sit in the low single digits. A coastal cottage bought for lifestyle reasons often yields less again as a long let, which is exactly why so many owners in those spots go short-term.
Run both sets of numbers for your own property before you get attached to either. A holiday let that grosses more than a long let can still lose the comparison once costs are subtracted.
Costs: where the holiday let money goes
Short-term letting carries a long list of running costs that long lets simply do not. Expect:
- Furnishing and equipping: beds, sofas, kitchen kit, a decent television, wifi, outdoor furniture, enough crockery. A two-bed needs to be lettable from day one, and the budget is not small.
- Changeovers: cleaning, laundry and restocking between every stay — potentially dozens of times a year.
- Utilities and broadband: you pay them, and guests use more than you would.
- Platform commission: the booking sites take a cut of every reservation.
- Insurance: specialist short-let cover with public liability, which costs more than a standard landlord policy.
- Wear and tear: carpets, paint and appliances age faster with weekly turnover.
- Business rates or council tax: whether you can move to business rates depends on letting thresholds, and those rules have changed in recent years. Check with the local authority and your accountant.
A long let carries fewer of these, but it is not free. You still fund repairs, an annual gas safety check, deposit protection and the gap between tenants. Use a letting agent for full management and you can add a percentage of the rent on top.
Rules, tax and paperwork
Both routes are regulated, and the rules in England have been moving. On the long-let side, tenancy law has shifted towards periodic tenancies with no-fault evictions removed, alongside minimum energy efficiency standards and licensing schemes in some council areas. On the short-let side, planning is the live issue: in parts of the country, using a home for short-term letting can require permission, local policies vary, and leasehold flats or restrictive covenants may prohibit it outright. Check before you buy, not after.
Tax deserves its own conversation. The favourable regime that furnished holiday lets once enjoyed has been withdrawn, and how mortgage interest is treated depends on how you structure things. Speak to an accountant. The difference between a sensible and a poor structure can be thousands of pounds a year.
Management: the real day-to-day difference
A holiday let is a hospitality job. Someone has to answer messages at nine in the evening, find a plumber on a Saturday in August, restock the dishwasher tablets and write a calm reply to a three-star review about a noisy seagull. Self-managed, that is a daily commitment through the season. Hand it to a local management company and you will pay a sizeable slice of your booking income for the privilege.
A long let asks far less of you. Weeks can pass without a phone call. The trade-off is that when something does go wrong — arrears, damage, a tenant who stops paying — the process is slow, formal, and you have fewer levers than a hotelier does.
Which one suits you?
Forget the spreadsheets for a moment and answer these honestly:
- Do you want a second job, or an investment that runs quietly in the background?
- Is the property somewhere people genuinely holiday? A terrace in central Ipswich is a long let. A cottage near Southwold beach is not.
- Do you want to use it yourself? Short lets allow personal stays; long lets do not.
- Can you absorb a poor season without needing the income?
- How will you fund it? Holiday let mortgages typically cost more and need larger deposits, and not every lender will
Photo: Anne-marie _ / Pexels